What Is a REIT?
A real estate investment trust (REIT) is a company that owns, operates or finances income-producing real estate. In the United States, REITs must distribute most of their taxable income to shareholders as dividends, which lets them avoid corporate income tax on that income.
REITs were created by U.S. Congress in 1960 to let individuals invest in large-scale real estate.
They have since spread to many countries.
How REITs Work
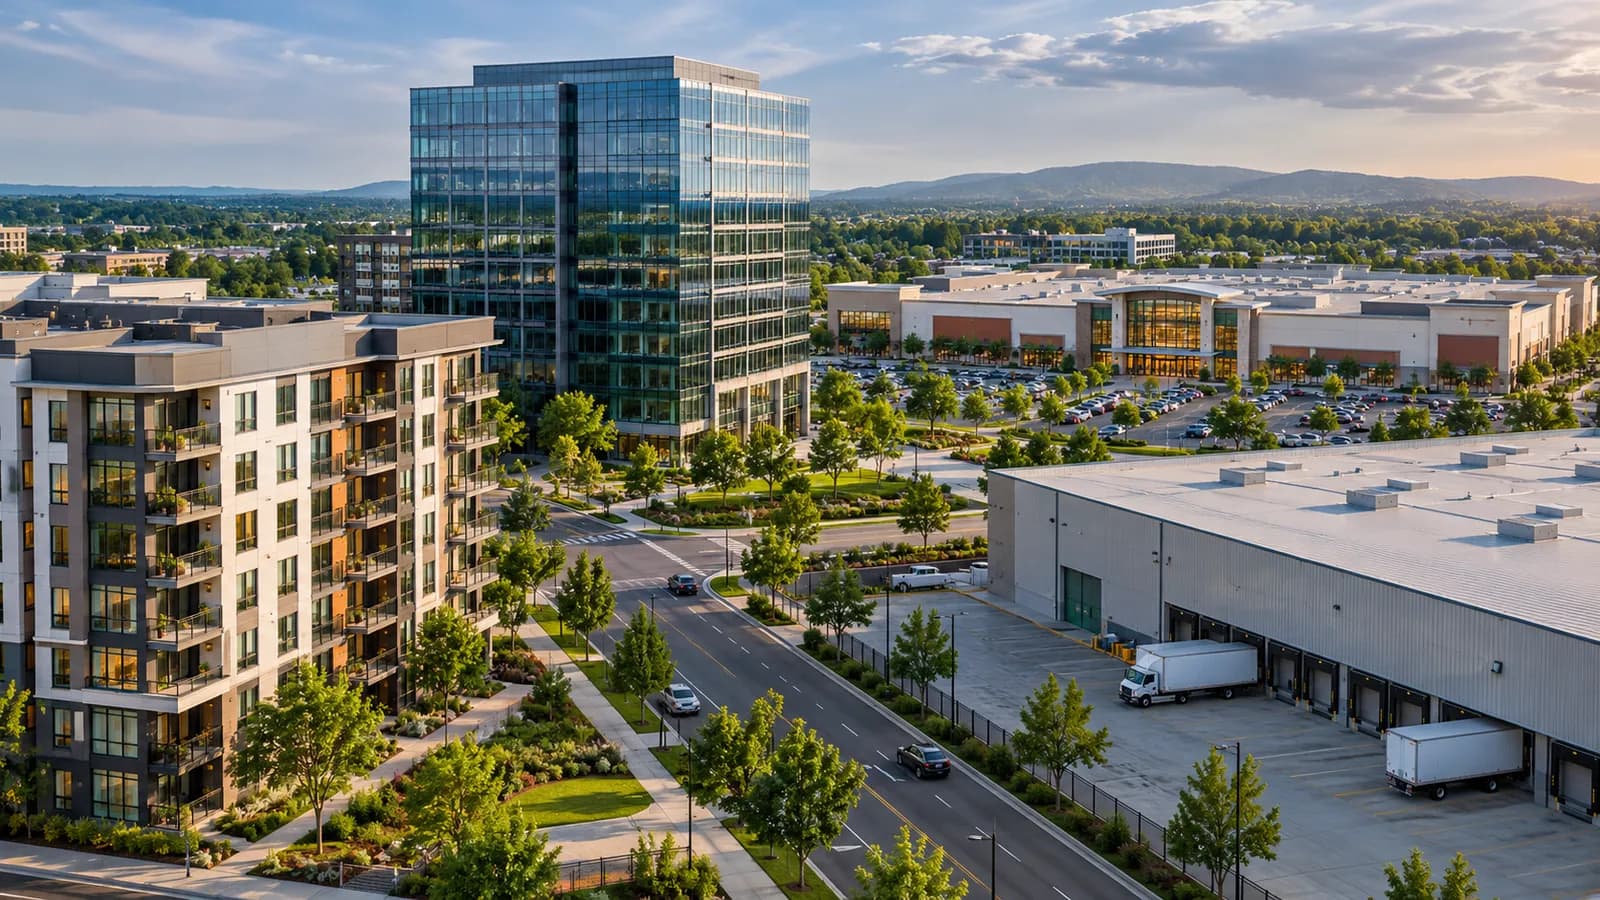
Equity REITs own properties such as apartments, offices, warehouses, retail centers, data centers and cell towers, and earn rent.
Mortgage REITs invest in mortgages and mortgage-backed securities and earn interest.
Publicly traded REITs trade on stock exchanges like other shares, while non-traded REITs do not.
Types of REITs
Equity REITs own property, mortgage REITs hold loans, and hybrid REITs do both.
Sectors include residential, office, industrial, retail, healthcare, data centers and towers.
Key Measures for Analyzing REITs
These measures are commonly used to assess a REIT:
- Funds from operations (FFO) and adjusted FFO
- Occupancy rate
- Dividend payout ratio
- Debt and interest coverage
- Net asset value
Risks and Limitations
REITs carry risks that differ from other stocks:
- Interest rate changes affecting borrowing and valuations
- Property sector downturns
- Tenant credit risk
- Dividends that are taxed as ordinary income
Lease Economics And Property Income
A lease turns a property into a stream of contractual payments, but the headline rent is only the starting point for understanding the economics. A lease specifies its term, payment schedule, permitted use and responsibility for costs. Some agreements include scheduled rent increases or adjustments tied to an index. Others give tenants renewal options or periods of reduced rent. The timing of cash receipts can differ from revenue recognized in financial statements, so a reader should distinguish the contractual payment schedule from reported rental revenue.
Operating expenses can be shared in different ways. Under a gross lease, the owner generally bears a larger share of property expenses within the quoted rent. Under a net lease, the tenant generally pays specified costs in addition to rent. Actual contracts vary, and labels alone do not reveal every obligation. Property taxes, insurance, maintenance and utilities can affect the amount an owner retains. Comparing properties therefore requires looking at both the rent collected and the expenses assigned to each party.
Occupancy also has more than one meaning. Physical occupancy describes space that is occupied, while leased occupancy can include space under a signed lease that a tenant has not yet taken possession of. A full building may still have modest income if rents are low or tenants receive concessions. The schedule of lease expirations adds another dimension: a concentration of leases ending together exposes more space to renegotiation at the same time. Tenant concentration matters because a single departure can have a disproportionate effect on a property.
Lease duration affects how quickly property income reflects changing conditions. Short leases come up for renewal more often, while long leases give both parties a longer contractual framework. Renewal decisions also depend on moving costs, the suitability of the space and local alternatives. When comparing newly signed rents with expiring rents, check whether the figures cover the same space and whether concessions and improvement allowances are included. A reported change in base rent alone does not describe the full cost or value of a lease agreement.
Reading Property Operating Results
Property owners often discuss net operating income, or NOI, as a measure of income from property operations before items such as corporate overhead, interest, income taxes and depreciation. Definitions and adjustments can vary, so the accompanying reconciliation is useful. NOI helps isolate property performance, but it is not cash available for shareholders. It does not by itself capture the cost of financing, corporate operations or all spending needed to maintain and improve buildings.
Same-property or same-store results focus on a comparable group of properties held across the periods being compared. This can help separate changes at existing buildings from the effect of acquisitions, sales or newly opened developments. The selection criteria matter: a property undergoing major redevelopment, for example, may be excluded. Reviewing the definition and the size of the included portfolio helps put the reported change in context. A portfolio-wide revenue increase can have a different explanation from growth at existing properties.
Capital expenditure disclosures help explain a further distinction between operating income and cash needs. Owners spend money to maintain roofs, mechanical systems and other building components, as well as to adapt space for tenants. Tenant improvements and leasing commissions can be substantial when space is relet. Some spending maintains existing earning capacity, while other spending expands or repositions a property, but the boundary is not always clear. Readers can examine the categories and management assumptions rather than treating all capital spending as interchangeable.
The cash flow statement provides another view of the business. Cash from operations reflects receipts and payments during the period, including changes in working capital, while investing cash flows generally include property purchases, development spending and sales. Financing cash flows show activities such as borrowing, repayment, share issuance and distributions. These categories answer different questions from an earnings measure. Comparing them over several reporting periods can reveal how the company funded its activities and whether timing or asset transactions shaped the cash balance.
Financing And Capital Allocation
A REIT can finance property ownership with a combination of debt and equity. Debt may be secured by particular properties or may be an obligation of the company without a claim on a specified asset. Loan agreements can contain covenants that require the borrower to maintain certain financial conditions. A balance sheet shows outstanding debt, while the notes and maturity schedule provide context about collateral, contractual terms and when principal comes due.
The structure of borrowing matters alongside its total amount. Fixed-rate debt generally has a stated rate for its term, while floating-rate debt resets with a reference rate under the loan agreement. A company may also use derivatives to manage some interest rate exposure. The notes can explain the instruments, their duration and the exposure they cover. Even fixed-rate borrowing can require refinancing when it matures, making the timing of maturities an important part of understanding financing needs.
Property purchases, developments, disposals and distributions compete for capital. Because a REIT distributes a substantial portion of taxable income, retained cash may be only one source of funding for these uses. Companies can also raise capital through borrowing, issuing shares or selling assets. Issuing shares increases the share count, so per-share figures can tell a different story from company-wide totals. Asset sales can provide cash while also removing the income previously generated by the sold properties.
Development introduces a different set of decisions from owning an occupied building. A project can require land, permits, construction funding and a period of work before tenants begin paying rent. Its economics depend on both the cost to complete the property and the terms on which space is leased. Disclosures may distinguish projects under construction from planned projects and completed properties. Reading the stated commitments alongside the progress of leasing helps explain how much work and spending remain under existing arrangements.
Structure Governance And Reporting
A REIT is a tax classification as well as a business structure. In the United States, qualification depends on meeting rules concerning income, assets, ownership and distributions. Taxable income is calculated under tax rules and differs from accounting net income and operating cash flow. Consequently, a distribution requirement based on taxable income should not be read as a requirement to distribute the same percentage of reported earnings or cash flow. Company filings describe the relevant policies and distributions.
Some REITs own properties through an operating partnership, with the publicly traded entity holding an interest alongside other partners. This arrangement can leave ownership interests outside the shares shown on the stock exchange. Financial statements may identify those interests separately as noncontrolling interests. When examining per-share measures or claims on the portfolio, it helps to read the ownership notes and understand how partnership units relate to common shares, including any conversion rights described in the filings.
Governance disclosures explain who makes decisions and how their interests are tied to results. A REIT may be managed by its own employees or by an external manager under a contractual arrangement. For an externally managed company, the agreement can specify management fees, expense reimbursements and termination provisions. Related-party transactions can also affect costs or property dealings. The proxy statement and financial statement notes provide a starting point for understanding oversight, compensation and potential conflicts of interest.
Conclusion: Understanding REITs
REITs offer a way to own a share of income-producing real estate through a traded security. Understanding property types, measures such as FFO and sensitivity to interest rates helps explain how they behave differently from other stocks.