Company Overview
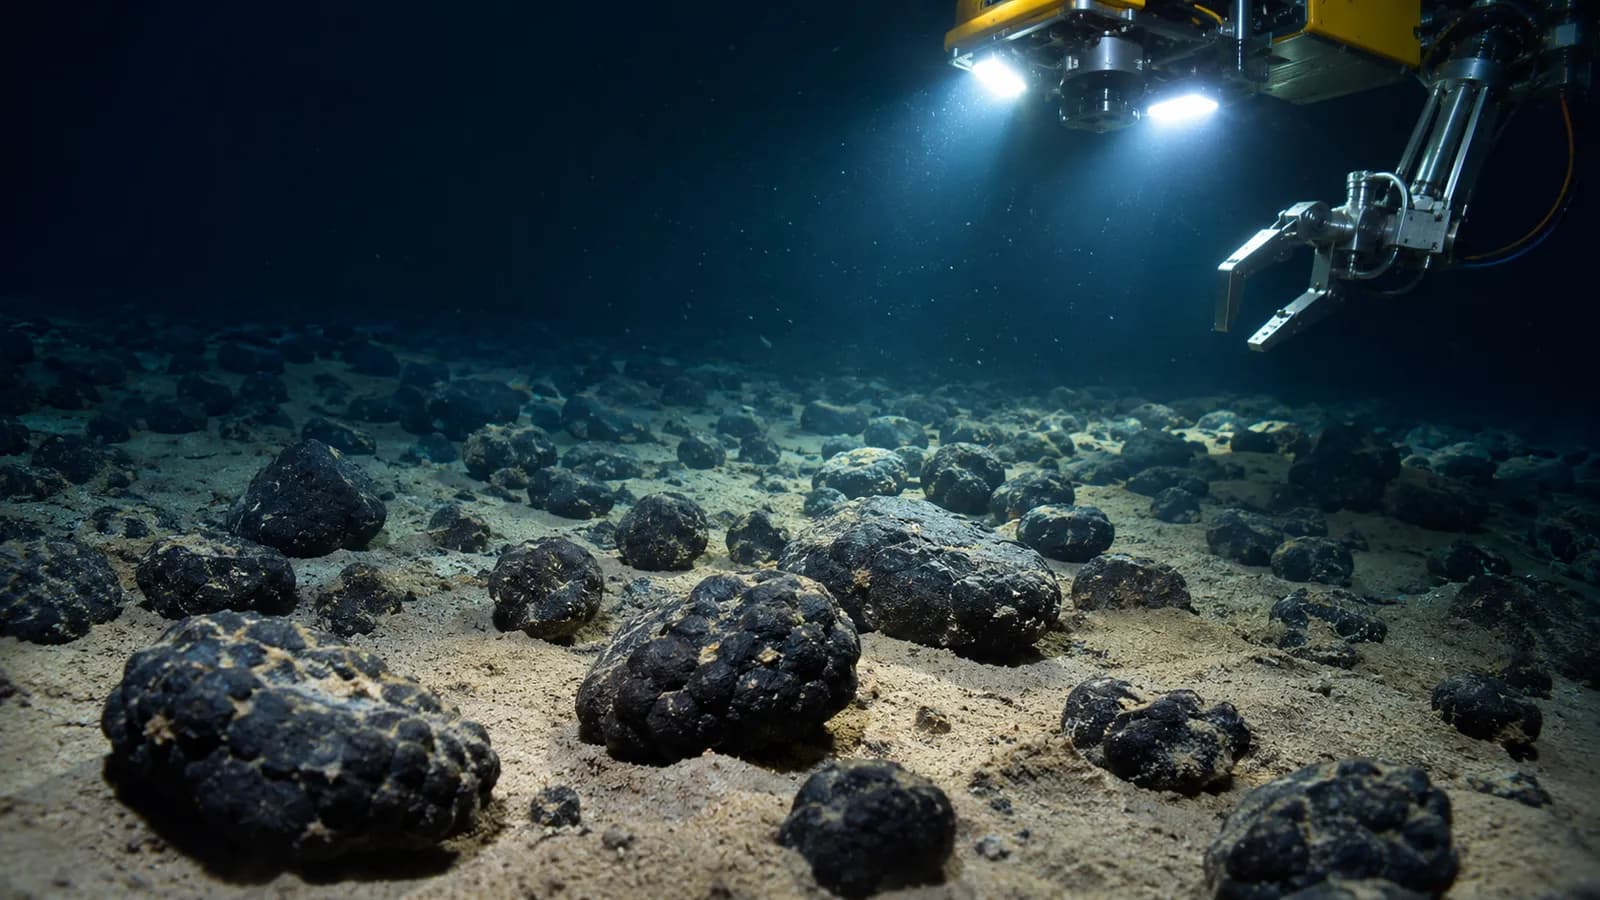
The Metals Company aims to collect polymetallic nodules from the deep seabed and process them into nickel, cobalt, copper and manganese. It trades on Nasdaq under the ticker TMC. Its project area is in the Clarion-Clipperton Zone of the Pacific Ocean.
The Metals Company was formed to pursue deep-sea nodule collection and became public through a merger with a special purpose acquisition company.
It has conducted pilot collection tests in the Pacific.
Latest Quarterly Update: Q3 2026
The Metals Company reported its third-quarter 2026 corporate update on November 12, 2026.
In a November 3, 2026 letter, NOAA said it expected to notify the company's U.S. subsidiary of its final determination on certification of its exploration application. NOAA's first public comment period closed on October 19, 2026.
As a pre-revenue company, TMC's spending and permit progress are the main reported measures.
Business Model and Revenue Drivers
Deep-sea mining is regulated internationally by the International Seabed Authority, and rules for commercial extraction have been slow to develop.
TMC has applied for a commercial recovery permit under U.S. law, a different regulatory path.
The company is pre-revenue and relies on funding from investors and partners.
Competitive Landscape
Other deep-sea mining companies and land-based miners of nickel, cobalt and copper are competitors.
Regulation and environmental concerns are major factors.
Revenue Growth and Financial Performance
When reviewing The Metals Company's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Regulatory permit progress
- Cash and funding
- Operating expenses
- Resource estimates
- Partnership agreements
Profitability and Earnings Quality
Revenue growth is only part of the picture. For The Metals Company, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of The Metals Company's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
TMC Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing The Metals Company relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for The Metals Company, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Regulatory uncertainty
- Environmental opposition
- Funding needs
- Metal price volatility
From Seabed To Metal
A nodule project involves several connected operations rather than a single mining step. A collector moves across the seabed and gathers nodules, which are transported through a riser system to a surface vessel. The material must then be handled, transported to shore and prepared for processing. Each interface can limit the capacity of the whole system: a vessel waiting for transport or a processing plant unable to accept material can leave equipment idle elsewhere. Reported equipment capacity is therefore different from sustained output across an integrated operation.
Processing determines how much of each contained metal becomes a saleable product. Recovery rates describe the share extracted, while product specifications determine whether a buyer can use the output in its own refining or manufacturing process. Moisture, impurities, energy use and waste handling can all affect processing economics. When evaluating technical disclosures, distinguish the metal contained in collected nodules from recovered metal and from finished product. These quantities describe different stages and should not be added together as though they were separate sources of output.
Land-based mines often move and process large amounts of rock to access ore. Nodules are already separate from bedrock, but collection takes place in deep water and requires specialized marine equipment. The comparison depends on the full chain, including vessel operations, transport, processing inputs and management of residual materials. A narrow comparison of ore grades or collection methods alone cannot show the total resources required by either approach.
Reading Resource Disclosures
A resource estimate describes mineral material whose quantity and characteristics have been assessed using geological evidence and stated assumptions. It is not the same as a reserve, which applies additional economic and technical criteria under the relevant reporting standard. Resource classifications also communicate differences in the amount and reliability of supporting data. Readers can examine the area sampled, sampling methods, assumed metal content and the boundaries used in the estimate to understand what has actually been measured and what has been inferred.
For nodules, the amount of material on the seabed and its metal content are distinct measures. Average abundance over an area does not imply that nodules are distributed evenly, while an average grade can conceal variation between samples. Mapping and collection planning must account for locations that cannot be accessed or that are excluded for other reasons. A resource estimate should therefore be read alongside its methodology and limitations, rather than treated as a direct measure of material available to a collector.
Changes between published estimates can result from new samples, revised boundaries, different technical assumptions or changes in the reporting framework. Comparing headline totals without identifying the cause can obscure whether the underlying geological evidence has changed. The accompanying technical report can also clarify which portions are included, how continuity between sample locations was assessed and whether the estimate refers to wet or dry material. Consistent units and definitions are essential when comparing separate disclosures.
Capital Spending And Commitments
An early-stage resource developer can incur expenditures for engineering, environmental studies, equipment design and organizational activities before a commercial facility exists. Financial statements may show some expenditures as expenses and others as assets, depending on their nature and applicable accounting rules. An expense reduces reported earnings in the period recognized, while capitalized costs generally appear on the balance sheet and may affect earnings over later periods. The cash flow statement helps show when cash actually leaves the business.
Commitments deserve attention alongside spending already recorded. Contracts for vessel services, equipment construction, processing work or other activities can create obligations that are not fully captured by a single period of cash outflow. Notes to the financial statements may describe payment schedules, termination provisions and contingencies. A useful reading separates binding commitments from proposed project budgets and identifies which amounts depend on a milestone or a final investment decision.
Funding arrangements can also have effects beyond the cash received. An equity issue changes the number of shares outstanding, while a convertible instrument can create shares if its conversion terms are met. Debt agreements may contain interest, repayment and covenant provisions; partner agreements can allocate project costs and future economic interests. The notes and agreement terms help explain these distinctions, including whether reported per-share figures reflect the potential effect of instruments that have not yet converted.
Environmental Baselines And Evidence
Environmental assessment begins with a baseline: observations of the physical and biological conditions in an area before an activity occurs. Researchers can then compare later observations with that baseline and with suitable reference areas. Sampling design matters because seabed communities and sediment conditions can vary across locations and over time. A limited observation period or sparse sampling may make it difficult to distinguish a change caused by an operation from natural variation.
Collection can disturb the seabed and suspend sediment in water. The extent and consequences of a sediment plume depend on factors such as particle properties, currents and the location of discharge. Assessments can examine where suspended material travels, how much settles and which organisms or habitats are exposed. Measures of plume concentration, spatial extent and duration answer different questions, so a single measure does not describe all potential effects.
Technical reports can distinguish observed effects during a test from modeled effects under different operating conditions. They can also describe monitoring methods, uncertainty, proposed controls and how those controls would be checked in practice. Recovery of a habitat is a separate question from the immediate footprint of disturbance. Evidence about one site or organism may not establish the response of every habitat or species, so the scope of each study matters when interpreting its conclusions.
Conclusion: Is TMC Stock Worth Analyzing in 2027?
The Metals Company has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. TMC is a company worth monitoring for what its results reveal about its business.