Company Overview
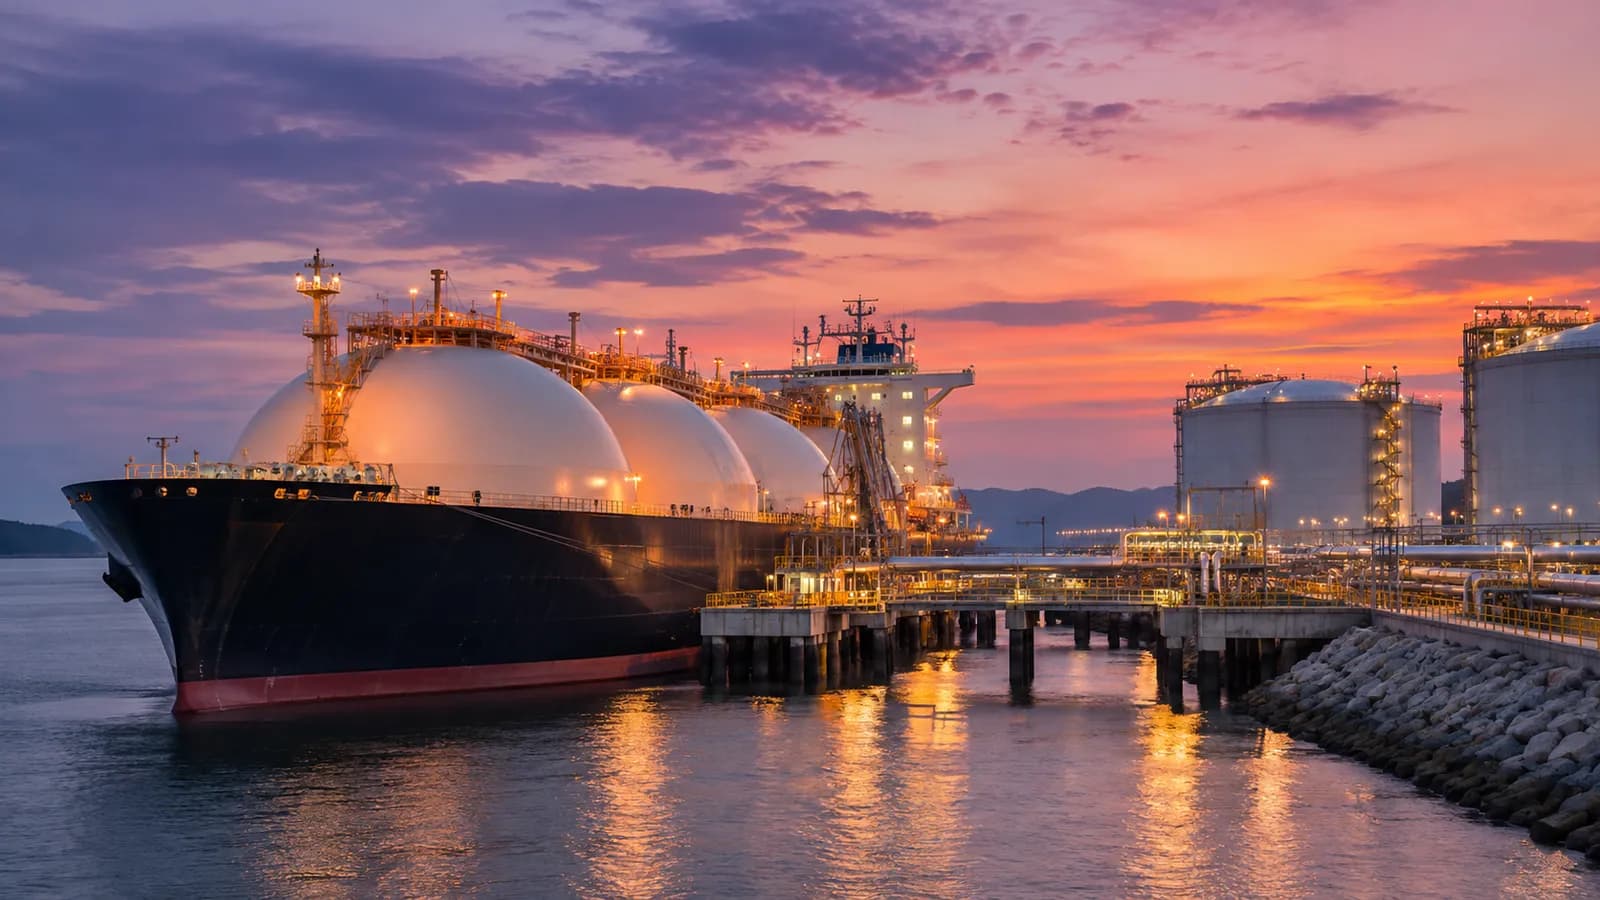
Shell is a global integrated energy company headquartered in London. Its shares trade in London and as American depositary shares on the NYSE under the ticker SHEL. Shell is one of the world's largest traders and producers of liquefied natural gas (LNG).
Shell was formed from the Royal Dutch and Shell Transport companies.
It unified its structure in London in 2022.
Shareholder Returns
Shell's latest dividend went ex-dividend on November 13, 2026.
Shell returns cash through both dividends and share buybacks, so total distributions are larger than the dividend yield alone suggests.
Business Model and Revenue Drivers
Shell reports segments including Integrated Gas, Upstream, Marketing, Chemicals and Products, and Renewables and Energy Solutions.
LNG is a major source of earnings and growth.
Shell returns cash through dividends and share buybacks.
Competitive Landscape
Shell competes with ExxonMobil, Chevron, BP and TotalEnergies.
Its LNG business is a key strength.
Revenue Growth and Financial Performance
When reviewing Shell's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Adjusted earnings
- Cash flow from operations
- LNG volumes
- Net debt
- Shareholder distributions
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Shell, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Shell's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
SHEL Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Shell relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Shell, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Oil and gas price swings
- Energy transition pressure
- Refining margin volatility
- Geopolitical risk
How Integrated Gas Contracts Work
LNG connects gas production to customers that cannot be reached economically by pipeline. The chain includes access to gas, liquefaction capacity, shipping, and regasification at the receiving market. Shell can participate at several points in that chain, sometimes alongside partners. Ownership interests, operating responsibilities, and contractual rights need not match, so the volume handled by a project is not automatically the volume attributable to Shell. Contract terms also determine how costs, output, and operational interruptions are shared among participants.
LNG sales agreements can differ in duration, destination flexibility, and the price reference used to calculate payments. Some arrangements link gas prices to oil benchmarks, while others refer to gas market prices. A portfolio participant may combine contracted supply, purchased cargoes, shipping capacity, and customer commitments. The resulting economics depend on the relationship among purchase terms, delivery obligations, transport costs, and sale terms, not simply on the headline price of gas in one market.
Trading results can reflect differences in location, timing, and contract terms as well as the physical movement of cargoes. A cargo can have a different value depending on where and when it is delivered, while storage and shipping offer ways to manage those differences. Trading also involves commitments and risk controls. Reported results should therefore be read with management commentary on market conditions and portfolio activity, rather than treated as a direct measure of production performance.
Upstream Project Economics
An upstream project typically moves from exploration and appraisal to development, production, and eventual decommissioning. Spending often occurs before a field generates revenue, and production facilities may operate for many years. Geological uncertainty, engineering design, access to infrastructure, and fiscal terms all shape the economics. A discovery alone does not establish commercial viability: the resource must be recoverable, and the expected output must support the cost of building and operating the necessary facilities.
Production volumes and reserves describe different things. Production measures output over a period, while proved reserves are estimated quantities that meet specified technical and economic criteria. Reserve estimates can change as fields are produced, projects are approved, knowledge of reservoirs improves, or relevant economic conditions change. Comparing changes in reserves with production can help explain how a portfolio is being replenished, but the result also depends on acquisitions, disposals, revisions, and the definitions used.
Many projects are run through joint ventures or governed by production sharing arrangements with resource owners. A host government may receive taxes, royalties, a share of output, or some combination of these. The distinction between gross field production and the portion attributable to Shell matters when interpreting operating disclosures. Decommissioning obligations also matter: removing facilities and restoring sites creates future costs, and accounting estimates for those obligations depend on assumptions about timing and expenditure.
Reading Segment Results
Integrated energy companies transfer materials and services across business boundaries. Crude produced upstream can be supplied to a refinery, and refined products can pass through trading and marketing channels. Segment reporting is designed to show the performance of each activity, but internal transfers and different accounting conventions can complicate comparisons with independent producers or refiners. The notes accompanying segment results explain how intersegment transactions are treated and how segment measures reconcile to group totals.
Refining turns crude oil into a mix of fuels and other products. Its operating result depends on the cost and quality of crude inputs, the prices of the products produced, energy consumed in processing, and the configuration and reliability of each facility. A commonly cited refining margin is a simplified indicator of the spread between product and crude prices. It cannot capture every refinery cost, product yield, maintenance event, or contractual arrangement that affects an actual result.
Chemicals operations transform hydrocarbon feedstocks into materials used across manufacturing and consumer industries. Feedstock choice, plant integration, product mix, and customer demand influence operating performance. Planned maintenance and unexpected outages can reduce utilization while some operating costs continue. When comparing periods, it is useful to distinguish a change in the margin earned on each unit from a change in the amount produced or sold, and to consider whether facilities were available throughout both periods.
Accounting For Long Lived Assets
Development spending is commonly recorded as an asset when accounting requirements are met, then charged to earnings over the useful life of the relevant asset. Depreciation, depletion, and amortization allocate past spending across periods; they do not represent the cash paid for new projects during the current period. As a result, a period with substantial project construction can show a different relationship between accounting expense and cash expenditure than a period dominated by established producing assets.
An impairment occurs when the carrying amount of an asset exceeds the amount recoverable under the applicable accounting rules. Estimating recoverable amounts requires assumptions that can include commodity prices, operating costs, production profiles, and discount rates. An impairment charge reduces reported earnings and the carrying value of assets, although it is generally not a cash payment in the period recorded. Later depreciation or depletion can also change because it is based on the revised carrying amount.
Asset sales can affect the income statement, cash flow statement, and future operating footprint in different ways. The gain or loss compares sale proceeds with the accounting carrying value, subject to transaction details; proceeds are not the same as recurring cash generated by operations. A disposal can also reduce future production or processing capacity. Reading the transaction note alongside segment disclosures helps distinguish the accounting effect of a sale from the activities that remain in the group.
Conclusion: Is SHEL Stock Worth Analyzing in 2027?
Shell has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. SHEL is a company worth monitoring for what its results reveal about its business.