Company Overview
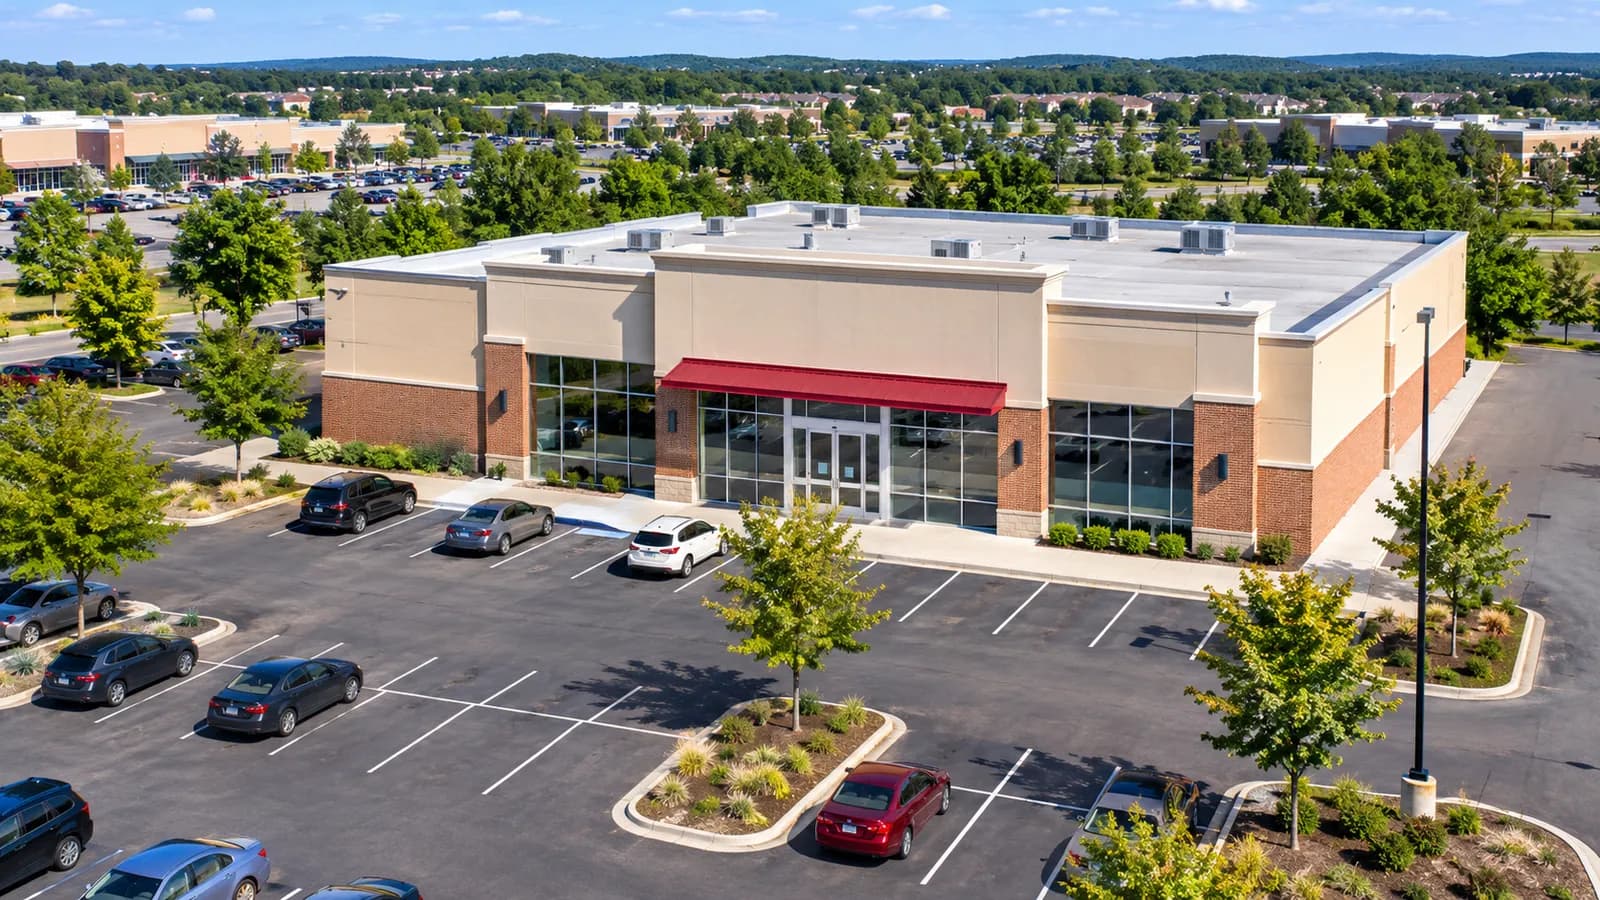
Realty Income is a real estate investment trust (REIT) that owns thousands of freestanding commercial properties leased to tenants under long-term net leases. It trades on the NYSE under the ticker O and is known for paying dividends monthly.
Realty Income was founded in 1969 and listed on the NYSE in 1994. It trademarked the name 'The Monthly Dividend Company'.
It has grown through acquisitions, including mergers with VEREIT and Spirit Realty Capital.
Latest Quarterly Results: Q3 2026
Realty Income reported third-quarter 2026 results in early November 2026.
GAAP net income included $113.9 million of gains on property sales, offset by $111.6 million of impairments. For REITs, AFFO is usually read alongside net income because depreciation reduces GAAP earnings.
Business Model and Revenue Drivers
In a net lease, the tenant pays most property costs such as taxes, insurance and maintenance, which makes rental income more predictable.
Tenants include grocery stores, convenience stores, dollar stores, drugstores and other retailers, as well as industrial and gaming properties.
Realty Income grows by acquiring properties, so its cost of capital compared with property yields is central to the analysis.
Competitive Landscape
Realty Income competes with other net-lease REITs such as NNN REIT, Agree Realty and W. P. Carey.
Its scale and investment-grade credit rating are key advantages.
Revenue Growth and Financial Performance
When reviewing Realty Income's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Adjusted funds from operations (AFFO) per share
- Occupancy rate
- Acquisition volume and yields
- Dividend payout ratio
- Debt and cost of capital
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Realty Income, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Realty Income's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
O Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Realty Income relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Realty Income, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Rising interest rates increasing borrowing costs
- Tenant bankruptcies
- Slower growth as the company gets larger
- Concentration in retail tenants
Lease Contracts And Rent Recognition
A lease specifies more than the initial rent. It can set scheduled rent increases, renewal options and conditions for transferring the lease to another operator. An option to renew gives the tenant a choice, while the landlord remains bound by the terms if the option is properly exercised. The difference between contractual rent and rent available on a new lease matters when assessing a property approaching expiration. A long remaining term can delay that reset, whether the existing rent is above or below prevailing terms.
Accounting revenue and cash rent can follow different paths. When a lease provides scheduled changes in rent, straight-line accounting generally spreads the contractual rent over the lease term. The resulting adjustment can increase reported rental revenue before the corresponding cash is collected. Financial statement notes and reconciliations help distinguish this noncash timing effect from cash actually received. Tenant concessions and lease amendments can complicate the comparison, so a change in reported rent should be read alongside the terms that produced it.
Tenant Credit And Property Location
A tenant's obligation to pay rent depends on the legal entity that signed the lease and on any guarantee supporting it. A recognizable store name does not necessarily mean that the parent company guarantees every location. Analysts can examine tenant disclosures, lease structures and the financial condition of material counterparties to understand where payment risk resides. Diversification by tenant count alone can obscure exposure if several tenants share a parent, depend on similar customers or face the same economic pressures.
The property itself provides a separate layer of analysis. A building designed for a narrow use may require alterations before another business can occupy it, while local zoning can constrain alternative uses. Access, surrounding businesses and the availability of comparable space also shape reletting prospects. If a tenant leaves, the owner may face a period without rent, brokerage fees or improvement costs. A portfolio occupancy percentage captures whether space is leased, but it does not reveal all of these property-level differences.
Reading Funds From Operations
Funds from operations starts with accounting earnings and makes prescribed adjustments intended to improve comparability for real estate businesses. In particular, real estate depreciation and certain gains or losses on property sales are typically reversed. The adjustment reflects the limitations of allocating a building's historical cost over an accounting life when assessing operating performance. It does not mean that buildings avoid physical wear or that every property retains its economic value.
AFFO begins with a related framework but uses additional adjustments, and its definition can vary among companies. Review the reconciliation in the company's filing to see which items management adds back or deducts, including noncash rent adjustments and recurring expenditures. Compare both the total measure and the per-share figure: issuance of shares can increase the denominator even when aggregate operating income rises. Consistent definitions across periods matter, as a changed adjustment can make a reported comparison harder to interpret.
Financing And Cash Flow Mechanics
A statement of cash flows separates operating activities from purchases and sales of property and from financing transactions. Acquisition spending appears in investing activities, while proceeds from issuing debt or shares appear in financing activities. Reading these sections together shows how property purchases were funded during a period. Sale proceeds can also fund spending, but they reduce the property base generating rent, so gross purchases alone do not describe the net change in the portfolio.
Debt maturity schedules show when principal comes due, while the notes describe interest rates, borrowing arrangements and restrictions. Fixed-rate debt generally keeps its stated interest expense stable until repayment or refinancing; floating-rate debt can reprice as its reference rate changes. The income statement may therefore respond to financing conditions on a different timetable from new borrowing. Looking at maturities together with available liquidity and contractual obligations gives a fuller picture than focusing on the average interest rate alone.
Property Sales And Portfolio Change
Selling a property changes both the asset base and the future stream of rent. The gain or loss reported on a sale compares proceeds with the property's carrying amount after accounting depreciation and other relevant adjustments. It is not the same as the total rent collected during ownership, nor does it by itself measure the performance of the entire portfolio. A large gain can reflect a low depreciated carrying amount as well as the terms of the sale.
Portfolio composition can also change through tenant moves, lease amendments and acquisitions of different property types. Comparing disclosures over several reporting periods can reveal whether rental income has become more dependent on particular industries or uses. Same-store or comparable-property measures, when provided, offer a way to examine properties included in both periods, although the selection criteria matter. Properties acquired, sold, redeveloped or otherwise excluded may have different experiences from those represented in that measure.
Conclusion: Is O Stock Worth Analyzing in 2027?
Realty Income has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. O is a company worth monitoring for what its results reveal about its business.