Company Overview
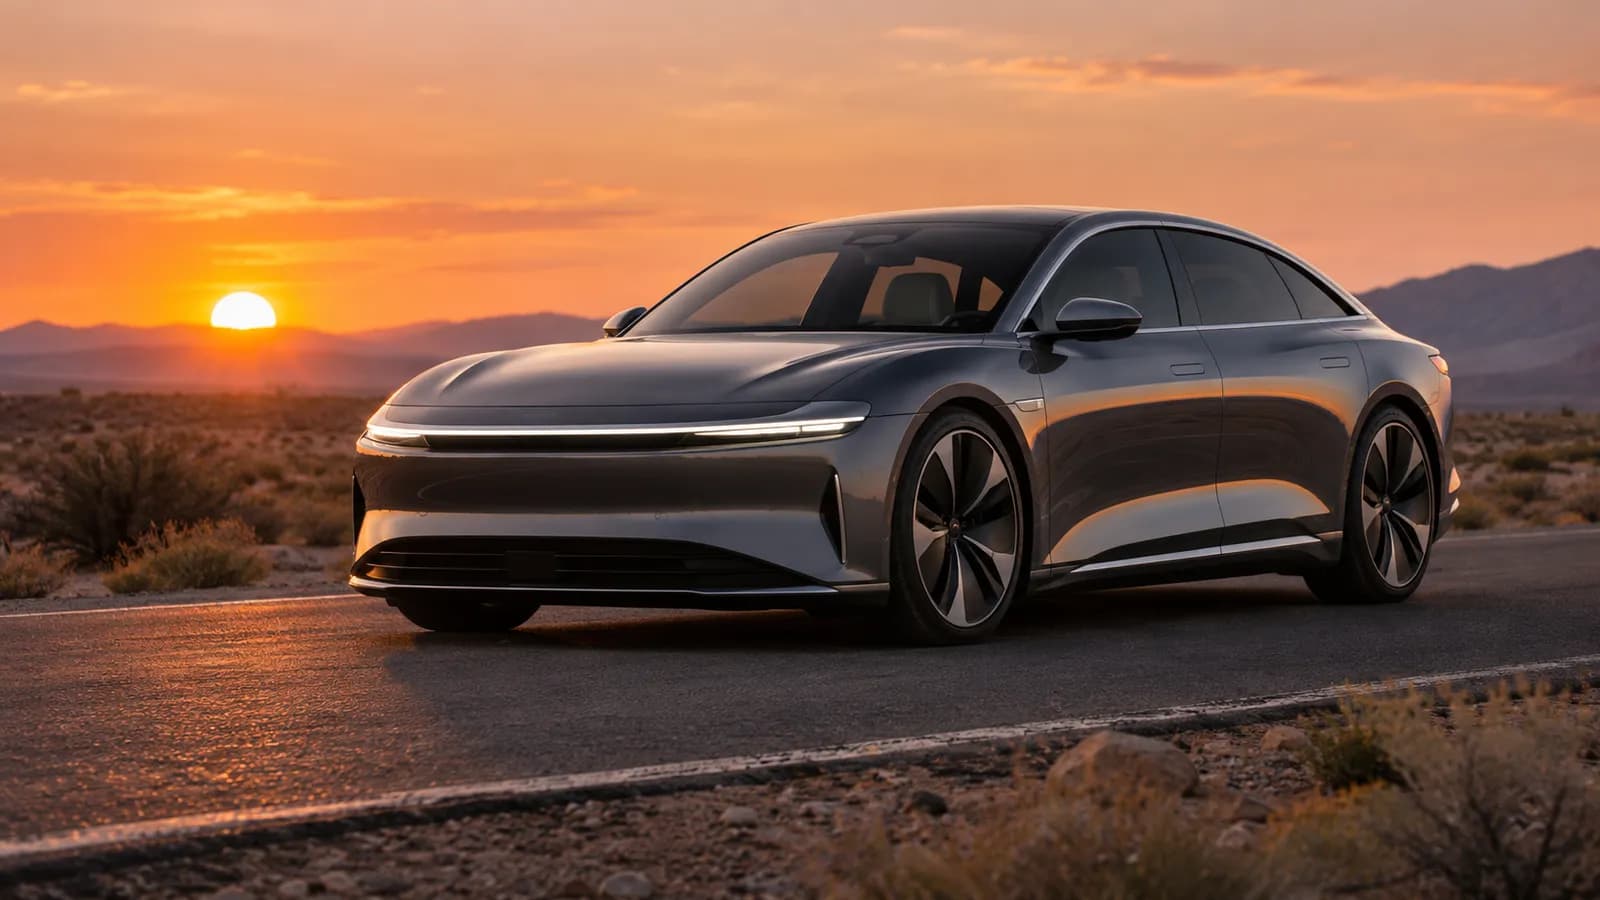
Lucid Group designs and builds luxury electric vehicles, including the Lucid Air sedan and the Lucid Gravity SUV, at its factory in Casa Grande, Arizona. It trades on Nasdaq under the ticker LCID. Saudi Arabia's Public Investment Fund is its largest shareholder.
Lucid was founded as Atieva, a battery technology company, and later shifted to building luxury electric vehicles under the Lucid name. It became public through a merger with Churchill Capital Corp IV.
Saudi Arabia's Public Investment Fund has repeatedly provided capital, and Lucid is building a factory in Saudi Arabia.
Latest Quarterly Results: Q3 2026
Lucid reported third-quarter 2026 results on November 9, 2026.
Deliveries fell 7% year over year, and free cash outflow was about $1.04 billion in the quarter. An expanded $1.75 billion facility from the Public Investment Fund extended the company's funding.
Business Model and Revenue Drivers
Lucid is known for battery efficiency and long driving range, and it develops much of its powertrain technology in-house.
Like other young automakers, Lucid has reported large losses while it scales production, and it relies on outside funding to cover cash burn.
The company is building a factory in Saudi Arabia and plans a midsize platform aimed at a lower price point.
Competitive Landscape
Lucid competes with Tesla, Mercedes-Benz, BMW, Porsche and other luxury EV makers.
Its strengths are efficiency, range and design, while its challenges include scale and cost.
Revenue Growth and Financial Performance
When reviewing Lucid Group's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Production and deliveries
- Gross margin per vehicle
- Cash burn and liquidity
- Funding from the Public Investment Fund and capital markets
- Progress on new models
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Lucid Group, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Lucid Group's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
LCID Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Lucid Group relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Lucid Group, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Continued losses and dependence on outside funding
- Competition in luxury electric vehicles
- Execution risk on production ramps and new models
- Changes in EV incentives and tariffs
From Orders To Recognized Revenue
A vehicle reservation, a completed sale and recognized revenue describe different stages of a transaction. A reservation can indicate interest without representing a completed purchase, and its terms can affect whether a customer proceeds. Revenue recognition depends on the contract and the transfer of control to the customer. Reading the revenue recognition note alongside delivery disclosures helps distinguish interest in a vehicle from transactions recorded in the income statement. Changes in reservation counts alone cannot establish how much revenue has been earned. Customer deposits, where applicable, are generally recorded as liabilities until the related obligation is satisfied or the deposit is returned.
The amount recorded for each vehicle can differ with configuration, optional equipment, discounts and other contract terms. Revenue can also include items beyond the initial vehicle sale, depending on the company's arrangements and accounting policies. For contracts containing multiple goods or services, accounting rules may require the transaction price to be allocated across separate obligations. Revenue for an obligation satisfied over time is recognized differently from revenue for a vehicle transferred at delivery. The notes to the financial statements explain the company's actual categories and policies. This distinction also matters when comparing vehicle revenue with total revenue, since their composition and timing may differ.
Manufacturing Costs And Capacity
Automotive manufacturing combines costs that move with each vehicle, such as components and freight, with costs that are less responsive to short-term output, such as factory depreciation and salaried manufacturing staff. When production changes, those fixed costs are spread across a different number of vehicles. This affects reported manufacturing cost per unit even if the underlying cost of parts is unchanged. A temporary shutdown, retooling or production of several configurations can also affect how efficiently a plant operates. Supplier contracts, labor practices and the mix of purchased and internally produced components also influence the cost structure.
Inventory accounting adds another layer to interpreting gross profit. Manufacturing costs are generally carried in inventory until the vehicles are sold, while certain abnormal production costs and inventory write-downs can be recognized in the period they arise. As a result, costs in a quarter's income statement need not match the vehicles built during that same quarter. Disclosures about inventory valuation, factory utilization and charges can help explain why a change in deliveries does not translate directly into a proportional change in gross profit. Comparing these disclosures across periods can reveal whether a reported change reflects current operations or the accounting treatment of earlier production.
Software Service And Ownership Economics
A modern electric vehicle combines mechanical systems with software that controls functions such as energy management, driver displays and vehicle updates. Developing that software in-house gives an automaker more control over how its components interact, but it also requires continuing engineering, testing and cybersecurity work. Software changes may be delivered after the initial sale, so the customer's experience and the manufacturer's responsibilities can extend well beyond the handover of the vehicle. The boundary between hardware and software also makes coordination with component suppliers an important part of vehicle development.
Warranty and service provisions are useful complements to sales figures. A manufacturer estimates the cost of covered repairs when it recognizes a vehicle sale and adjusts those estimates as experience develops. A change in the provision can reflect new sales, repairs completed or revised assumptions about future claims. Service capacity, parts availability and repair complexity also shape the ownership experience and the cost of supporting vehicles already on the road. The warranty note can show how the obligation changes from one reporting period to another. Recall costs and warranty costs may have different causes, so their individual disclosures provide useful context for interpreting changes.
Capital Spending And Accounting
Designing a vehicle and preparing a factory involve different accounting treatments. Research and development costs are generally expensed as incurred under US accounting rules, while eligible spending on manufacturing equipment and facilities is recorded as an asset and depreciated over its useful life. The distinction affects the timing of expenses in reported earnings. A period with substantial development work can therefore look different from a period with substantial equipment purchases, even when both activities support the same vehicle program. Accounting treatment depends on the nature of the expenditure, so the financial statement notes are important when comparing programs or companies.
Cash flow disclosures provide another view of those activities. Purchases of property and equipment generally appear in investing activities, while depreciation is a noncash expense added back when operating cash flow is reconciled from net income using the indirect method. Adding back depreciation does not reverse the original cash spent on the asset. Examining capital expenditures together with the asset and depreciation notes helps connect spending on facilities and tooling with the expenses recognized as those assets are used. Commitments for equipment or construction can also provide context because an agreed purchase may precede the associated cash payment.
Conclusion: Is LCID Stock Worth Analyzing in 2027?
Lucid Group has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. LCID is a company worth monitoring for what its results reveal about its business.