Company Overview
Hyundai Motor is South Korea's largest automaker, selling Hyundai and Genesis vehicles and holding a large stake in Kia. Its shares trade on the Korea Exchange under 005380, with global depositary receipts in London.
Hyundai Motor was founded in 1967.
It became one of the world's largest automakers.
Latest Quarterly Results: Q3 2026
Hyundai Motor reported third-quarter 2026 results on October 29, 2026.
Operating profit rose despite lower volumes, helped by favorable exchange rates, cost savings and product mix.
Business Model and Revenue Drivers
Hyundai Motor Group, including Kia, is among the world's largest automakers by volume.
Hyundai is expanding U.S. production, including its Georgia Metaplant.
Tariffs and currency movements affect profitability.
Competitive Landscape
Hyundai competes with Toyota, Volkswagen, GM, Ford and others.
Its EV lineup is a strength.
Revenue Growth and Financial Performance
When reviewing Hyundai Motor's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Vehicle sales
- Operating margin
- EV sales
- Currency effects
- Shareholder returns
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Hyundai Motor, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Hyundai Motor's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
005380 Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Hyundai Motor relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Hyundai Motor, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Tariffs
- Currency swings
- EV competition
- Labor relations
From Factory To Customer
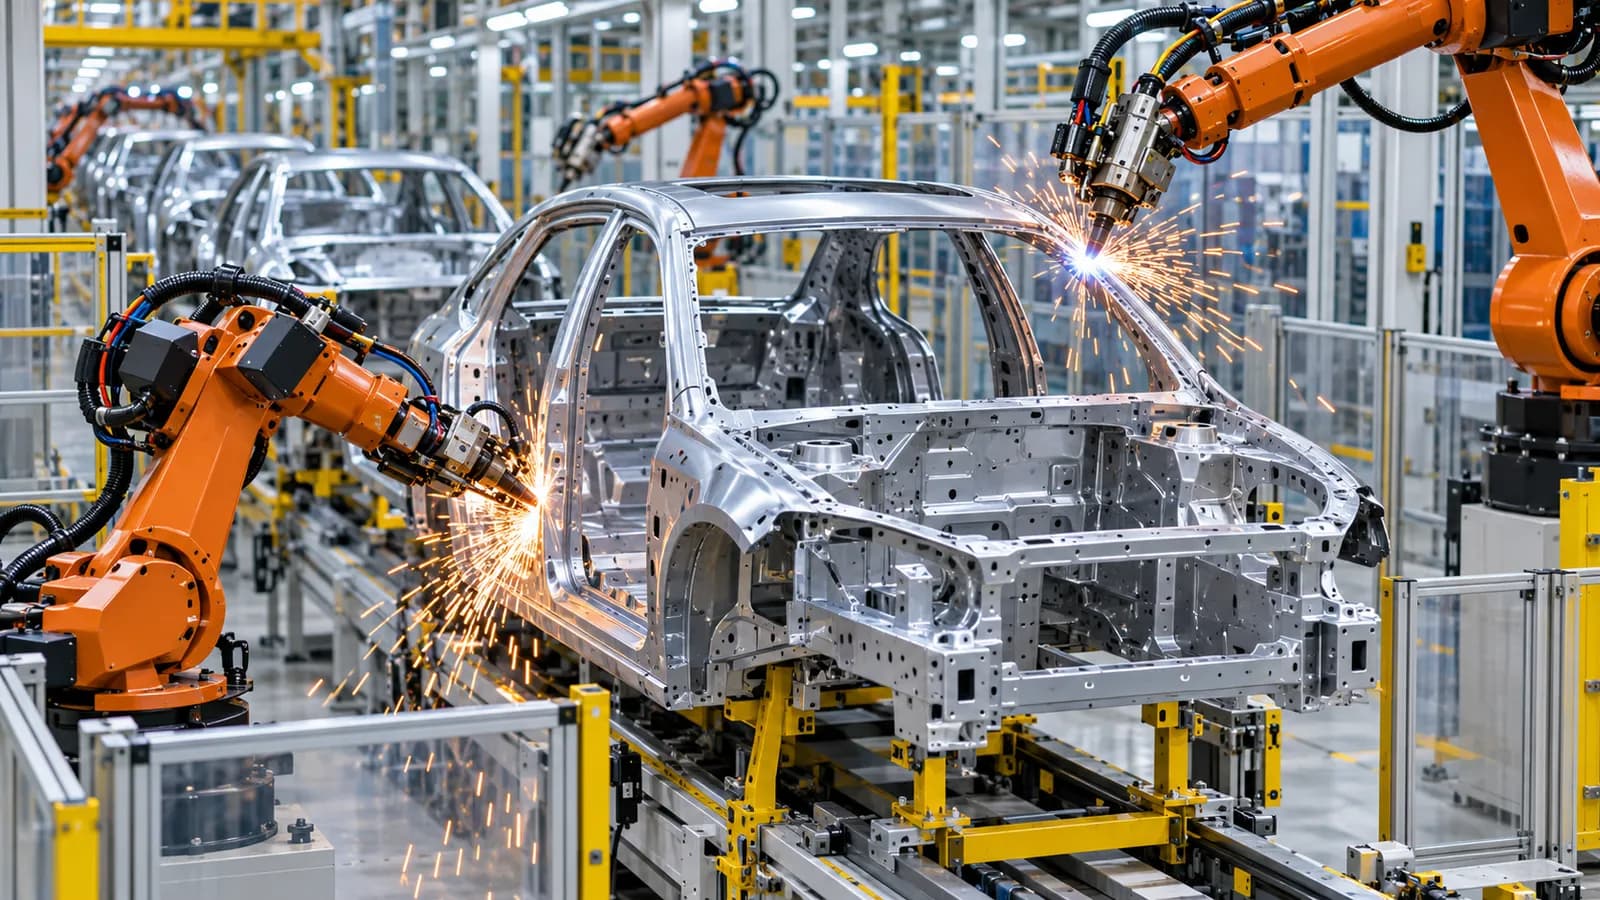
An automaker's reported vehicle shipments and the number of vehicles registered by final customers measure different stages of distribution. Wholesale generally refers to vehicles supplied into the sales channel, while retail sales describe purchases by end users. Dealers can receive cars before finding buyers, so the two measures can diverge as dealer stocks change. Comparing them over several periods helps explain whether production and shipments are moving in step with customer purchases. Definitions and geographic coverage should be checked in the company's reporting before comparing the series.
A vehicle sale is also more than the assembly of a car. Automakers coordinate components, shipping, warranty support and relationships with dealers or other retail partners. The economics of a model depend partly on how its equipment and manufacturing costs relate to its selling price. Optional features and higher specification versions can change the revenue generated per vehicle, while discount programs and sales incentives can reduce the amount retained. Average revenue per vehicle therefore reflects a changing basket of products and transactions rather than a simple price change.
Production capacity brings a separate operating consideration. Factories carry substantial costs for equipment, facilities and staff, and these costs do not necessarily fall in proportion to output. When a plant produces more vehicles, some fixed costs can be spread across more units. When output falls or a model change interrupts production, the cost per unit can rise. Capacity utilization should be interpreted alongside planned maintenance, launches and the mix of vehicles made at each facility, since a single utilization figure cannot explain every change in manufacturing efficiency.
Financing And Consolidated Accounts
Automotive groups can provide financing to customers and dealers as well as manufacture vehicles. A financing business earns income from lending or leasing, but it also incurs funding costs and bears credit risk. Its assets and liabilities can therefore look very different from those of a manufacturing operation. When segment information is available, separating automotive and financial services results helps explain why consolidated debt, interest income and cash flows may move in ways that vehicle production alone does not explain.
A vehicle lease introduces a residual value: the estimated value of the vehicle when the lease ends. Lease accounting and eventual results depend on assumptions about depreciation and the vehicle's condition and disposal proceeds. Credit losses are another distinct consideration, because borrowers may miss payments or default. Readers can examine disclosures on financing receivables, allowances for expected losses and leased assets together. Changes in these items need context from the size and composition of the financing portfolio, not just the direction of the reported balance.
Hyundai Motor's stake in Kia also requires care when reading consolidated results. A stake in another company does not make all of that company's sales Hyundai Motor revenue. The accounting treatment depends on the nature of the relationship and applicable accounting rules. Where the equity method applies, a share of the investee's profit or loss is recognized separately from the investor's own operating sales. The notes and income statement identify the treatment, making it possible to distinguish vehicle operations from income associated with an ownership interest.
Product Development And Supply Networks
Vehicle platforms provide a shared engineering base for multiple models. Common structures, components and software can spread development and purchasing costs across a wider range, while different body styles and interiors give models separate identities. Standardization also creates trade-offs: a component problem or production interruption can affect several models that use the same design. Platform sharing is therefore useful to consider alongside recalls, launch schedules and the range of models built on common parts.
Automakers rely on suppliers for materials, electronic components and complete assemblies. Some parts can be sourced from several manufacturers, while specialized components may have fewer alternatives or require extensive testing before substitution. A shortage can constrain assembly even if most other parts are available. Supplier relationships also involve quality control and coordination of delivery schedules, because a defect or delay upstream can interrupt production downstream. These mechanisms help explain why factory output is not determined solely by the manufacturer's own capacity.
Research and development supports new vehicles, powertrains, safety features and software. Financial statements may show some development spending as an expense and recognize some qualifying costs as an asset, depending on the accounting rules and the nature of the project. Capitalized costs are generally charged to earnings over time through amortization or depreciation, subject to the relevant accounting treatment. Reading the accounting policy and notes alongside research spending helps distinguish cash committed to development from the amount recognized in a particular period's earnings.
Ownership Economics And Service
The relationship with a vehicle customer continues after delivery through maintenance, replacement parts, repairs and warranty service. These activities have different economics from selling a new vehicle, and the manufacturer, dealers and independent repair businesses may each perform different roles. A larger population of vehicles already on the road can support demand for parts and service even when new vehicle sales fluctuate. The age and model mix of that population matter because service needs and parts requirements change over a vehicle's life.
A warranty is a promise to address covered defects under specified conditions. Manufacturers estimate the cost of meeting those obligations and recognize provisions in their accounts. Actual repair frequency, parts costs and labor costs can differ from the original estimate, requiring revisions. Recalls and other quality campaigns can also create costs and affect customer experience. The warranty provision and related disclosures are useful to read together with changes in sales volumes and the mix of vehicles covered, since the balance alone does not measure product quality.
Electric and combustion vehicles have different component and service profiles. An electric drivetrain has fewer conventional engine components, while its battery, power electronics and charging-related systems introduce their own design and service requirements. The impact on a manufacturer's parts and service activities depends on which work it performs, how its dealer network is organized and the composition of vehicles in use. Comparing revenue streams across powertrain types therefore requires attention to the entire ownership period, rather than assuming that every vehicle creates the same pattern of after-sales business.
Conclusion: Is 005380 Stock Worth Analyzing in 2027?
Hyundai Motor has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. 005380 is a company worth monitoring for what its results reveal about its business.