Company Overview
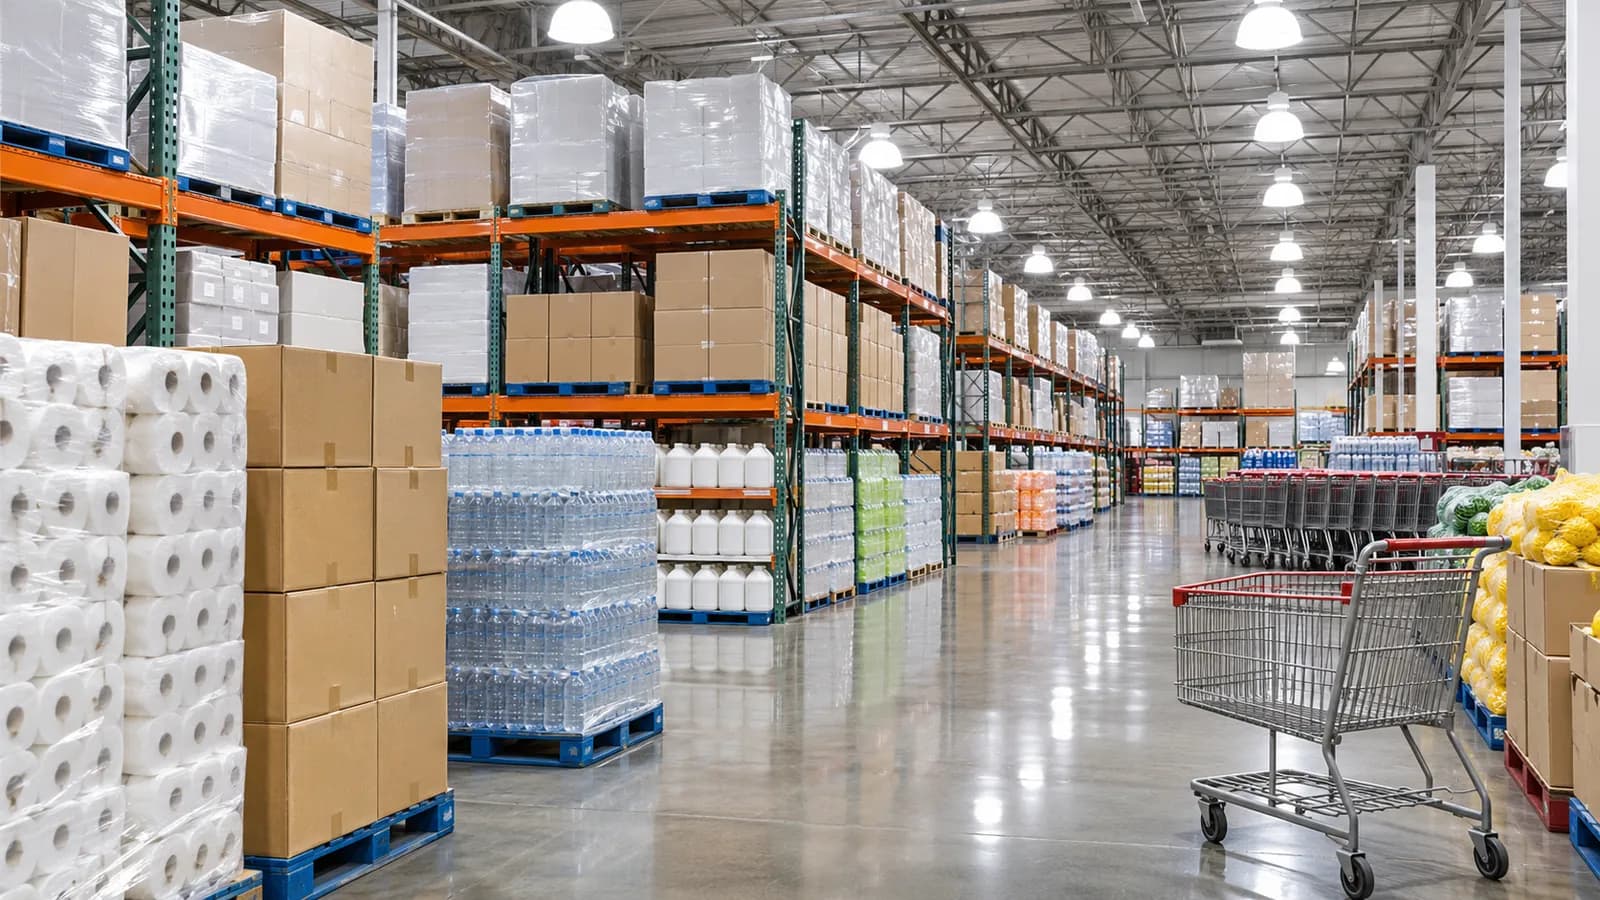
Costco operates membership warehouse clubs that sell groceries, household goods, electronics and other products in bulk at low prices. It trades on Nasdaq under the ticker COST.
Costco opened its first warehouse in Seattle in 1983 and merged with Price Club in 1993.
It has grown into one of the world's largest retailers.
Fiscal 2026 and Fourth-Quarter Results
Costco reported fiscal fourth-quarter and full-year 2026 results (year ended August 30, 2026) on September 24, 2026.
Fourth-quarter results included a one-time benefit of $0.15 per share from tariff refunds. Membership fee growth was driven by higher Executive membership penetration and member growth.
Business Model and Revenue Drivers
Membership fees provide a large share of operating income, allowing Costco to keep product markups low.
Costco's private label, Kirkland Signature, offers quality products at lower prices.
Costco has high membership renewal rates and expands by opening new warehouses.
Competitive Landscape
Costco competes with Walmart, Sam's Club, BJ's, Amazon and grocery chains.
Its membership model and low prices are key strengths.
Revenue Growth and Financial Performance
When reviewing Costco's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Comparable sales growth
- Membership fee income and renewal rates
- Number of warehouses
- Gross margin
- E-commerce growth
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Costco, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Costco's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
COST Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Costco relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Costco, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Competition from Walmart, Sam's Club, Amazon and others
- Valuation sensitivity
- Cost inflation and supply chain issues
- Changes in consumer spending
Warehouse Economics And Product Selection
A warehouse club organizes selling around a relatively narrow assortment and large packages. Each product occupies valuable floor and storage space, so its sales rate matters alongside the margin earned on each unit. Concentrating purchases among fewer items can simplify ordering, receiving and shelf replenishment. It can also give a supplier access to substantial volume, while making the retailer more dependent on the availability and appeal of the items it chooses to carry.
Large packages change the economics for both the retailer and the household. Fewer individual packages can reduce handling per unit sold, while customers take on more storage and must use the contents before they expire. The apparent saving per unit is therefore different from the saving on a household's actual consumption. Package size, available space and waste all affect how attractive a warehouse purchase is to a member.
The warehouse format also combines regularly purchased staples with changing selections of discretionary merchandise. Staples give members reasons to return, while changing assortments can encourage exploration during a visit. For an analyst, category mix helps explain why two periods with similar total sales growth can have different merchandise margins and operating demands. A shift toward bulky staples, for example, can affect space use and transaction patterns differently from a shift toward seasonal goods.
Reading Membership Economics
Membership is a relationship that extends beyond the day a fee is collected. The initial payment grants access for a defined period, so accounting generally recognizes the fee over the membership term rather than treating all of it as income immediately. The balance sheet can therefore contain deferred membership fees representing service periods that have not yet elapsed. Cash collected and fee income reported in a particular period need not match.
Changes in fee income can reflect several distinct forces: the number of paid memberships, the mix of membership types, fee levels and the timing of recognition. A higher total alone does not identify which force mattered most. Reading management's discussion alongside membership counts and renewal disclosures helps separate an expanding member base from a change in the composition of existing members. Definitions and reporting periods should be checked before comparing figures across companies.
Renewal rates describe retention among memberships eligible for renewal, while member counts describe the size of a population at a point in time. They answer different questions. A stable renewal rate can coexist with changing membership counts when new sign-ups or the pool eligible to renew change. Executive membership also carries a rewards feature, so assessing that tier requires attention to both its fee contribution and the related rewards expense.
Supplier Relationships And Inventory Flow
Costco's purchasing model connects suppliers, distribution facilities and warehouses. Suppliers must meet requirements for product specifications, packaging and delivery, and a limited assortment can make gaining or retaining shelf space consequential. The retailer's purchasing scale can support negotiations over terms, but scale does not eliminate exposure to a disrupted factory, a poor harvest or a transportation bottleneck. The ability to substitute products and suppliers depends on the category.
Inventory turnover measures the relationship between merchandise sold and inventory carried. Faster turnover can reduce the time cash is tied up in goods, although a very lean inventory position may leave less room to absorb supply interruptions. Turnover should be interpreted with changes in product mix and seasonal ordering: durable merchandise and fresh food can move through the system at different speeds, and a single balance sheet date may not represent a typical period.
Payment terms add another dimension to the cash cycle. Merchandise may be sold before the supplier invoice is paid, allowing sales receipts to help finance inventory. Accounts payable, however, is an obligation that eventually comes due, not a permanent source of earnings. Comparing inventory, payables and operating cash flow over several periods can clarify whether cash generation reflects sales activity or a temporary change in the timing of payments.
Interpreting Sales Across Channels And Markets
Reported sales changes combine the number of transactions with the amount spent per transaction. Those measures can move in opposite directions: more visits can coincide with smaller baskets, or fewer visits with larger baskets. Category mix also matters because a transaction containing electronics has a different value from one containing everyday groceries. Separating traffic from basket size gives a clearer account of how shoppers produced a reported sales change.
Online sales and warehouse sales involve different fulfillment choices and costs. An online order may require picking, packing, delivery and returns handling, while a warehouse visit shifts much of the selection and transport work to the customer. Some digital orders can complement a warehouse visit rather than replace it. When reading channel growth, it is useful to look for changes in fulfillment expense and the types of goods sold, not just the sales total.
International operations add another layer to reported comparisons. Local sales are translated into the reporting currency, so exchange rate movements can change the reported amount even when activity in the local currency is unchanged. Results that exclude currency effects help isolate operating movement, but they do not remove other differences between markets, such as product preferences, regulations or warehouse maturity. Both reported and adjusted measures provide useful context.
Conclusion: Is COST Stock Worth Analyzing in 2027?
Costco has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. COST is a company worth monitoring for what its results reveal about its business.