Company Overview
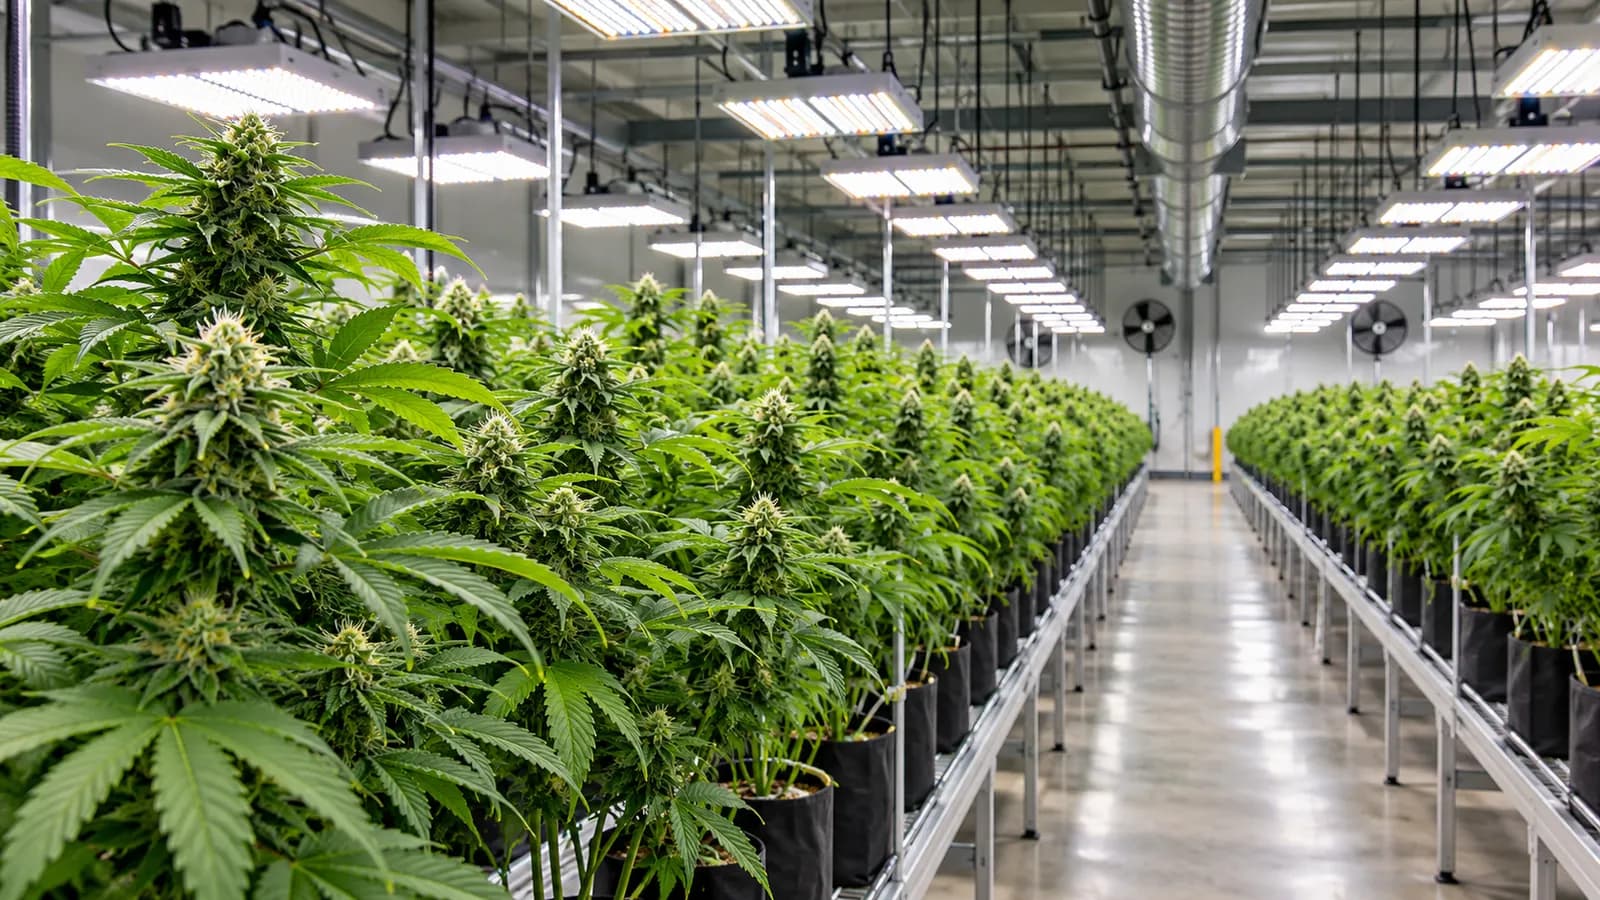
Canopy Growth is a Canadian cannabis company that sells medical and recreational cannabis and owns Storz & Bickel, a maker of vaporizers. It trades on Nasdaq under the ticker CGC and on the Toronto Stock Exchange.
Canopy Growth was founded in 2014 and became one of the first cannabis companies listed in the US.
Constellation Brands invested heavily before exiting.
Recent Update
Canopy Growth reported fiscal second-quarter 2027 results on November 6, 2026.
The shares were down about 47% over the past year and traded near their 52-week low in November 2026.
Business Model and Revenue Drivers
Canopy has restructured repeatedly, closing facilities and selling businesses to reduce costs.
It holds an interest in Canopy USA, a structure designed to gain U.S. cannabis exposure when federal law allows.
The company has reported net losses and has raised capital through share issuance.
Competitive Landscape
Canopy competes with Tilray, Aurora, SNDL and others.
Price compression affects all Canadian producers.
Revenue Growth and Financial Performance
When reviewing Canopy Growth's reported results, these measures give the clearest view of growth, profitability and cash generation:
- Net revenue by segment
- Gross margin
- Adjusted EBITDA
- Cash and debt
- Share count
Profitability and Earnings Quality
Revenue growth is only part of the picture. For Canopy Growth, it helps to check whether growth comes from higher volumes, higher prices or acquisitions, and whether margins are widening or narrowing as the business scales.
Reported earnings can include one-time items such as restructuring charges, asset sales, tax effects or legal settlements. Separating these from recurring operating results, and comparing like-for-like periods, gives a more reliable view of underlying profitability.
Balance Sheet, Debt and Financial Stability
A review of Canopy Growth's financial position starts with cash, total debt, lease obligations and how operating cash flow compares with capital spending. A business that funds its investment from its own cash flow is in a different position from one that relies on borrowing or issuing new shares.
Changes in inventory, receivables and working capital are also worth monitoring, because they can absorb cash and signal shifts in demand before they appear in revenue.
CGC Stock Valuation Analysis
Measures such as the price-to-earnings ratio, price-to-sales ratio and enterprise value to EBITDA describe how the market is currently pricing Canopy Growth relative to its results.
However, a single valuation ratio cannot establish whether a stock is undervalued or overvalued. Earnings quality, free cash flow, margins, competitive position and the growth needed to support the current price all need to be considered together, and compared with similar companies.
Business Outlook and Investment Risks
Management guidance and industry conditions shape expectations for Canopy Growth, but guidance is an estimate rather than an established outcome. Several uncertainties are specific to this business:
- Cannabis price compression
- Continued losses
- Dilution
- Regulatory uncertainty
Routes To Cannabis Consumers
Canadian recreational cannabis reaches consumers through a regulated system in which provincial and territorial authorities play a central role. Rules governing distribution and retail differ by jurisdiction, so a producer's access to shelf space and customers depends partly on where its products are listed. A listing makes a product available through a channel, but it does not guarantee that stores will carry it or that consumers will choose it. The distance between shipment to a distributor and a final retail sale matters when interpreting reported sales.
Retail assortment also shapes the economics of a product. Stores have limited shelf space and must choose among formats, brands and package sizes. A producer may support distribution with product education and trade relationships, subject to restrictions on promotion. Changes in assortment can alter the mix of products sold even when overall consumer demand is stable. Segment disclosures and management commentary can help distinguish a broad change in demand from a change in channel access or the timing of orders.
Medical cannabis follows a different route from the adult-use market. Patients access products under a medical framework, and the purchase process involves different documentation and service needs. Medical customers may value consistency of formulation, reliable availability and support in navigating orders. These features affect the work required to serve the channel. Comparing medical and recreational sales therefore involves more than comparing revenue: their customer relationships, distribution processes and product requirements can differ.
From Cultivation To Finished Product
Cannabis production starts with biological material, so output varies with cultivation conditions and the characteristics of each plant. Harvested material then requires drying, processing, testing and packaging before it can be sold. Some products undergo additional extraction or formulation. Each stage consumes labor, materials and facility capacity, while quality controls determine whether output can be released. A production problem can therefore affect both the quantity available for sale and the cost assigned to usable inventory.
Different formats use the supply chain in different ways. Dried flower relies on cultivation and handling, while extracts and other processed formats add manufacturing steps and ingredients. Packaging and compliance requirements also differ by format. A shift in sales mix can change reported gross margin even if the efficiency of each individual production process is unchanged. Reading the accompanying notes for inventory write-downs and production costs helps explain whether a margin change reflects mix, utilization or charges against inventory.
Capacity utilization is especially relevant because facilities carry costs even when they are not fully used. When output is spread across fewer saleable units, the cost attributed to each unit can rise. Conversely, a larger production run does not automatically improve economics if the resulting goods cannot be sold before their quality or marketability deteriorates. Operational efficiency must be considered alongside product quality, timing and the ability to match production with orders.
Vaporizer Business Economics
Storz & Bickel's devices have a different economic profile from consumable cannabis. A device sale transfers a durable product to a customer, while accessories and replacement parts can create additional transactions over the life of that device. The timing of those transactions need not match cannabis purchasing patterns. Product design, manufacturing quality, distribution and customer support all influence the cost of serving the market. Revenue from hardware should therefore be interpreted in the context of device launches and channel ordering patterns.
A hardware maker also manages warranty obligations and returns. When a company estimates future service costs associated with products already sold, those estimates can affect current expenses and liabilities. Changes in warranty assumptions may make a period's results harder to compare with earlier periods. Inventory composition matters too: finished devices, components and replacement parts serve different purposes, and a design change can affect the usefulness of parts held for older models.
The vaporizer category also illustrates why brand reputation and intellectual property matter operationally. Product reliability, ease of use and after-sales service can influence customer experience, while patents and other protections may support a particular design approach. Those protections do not remove the need to manufacture consistently or maintain distribution relationships. When segment information is available, examining both revenue and operating costs can show how the device business contributes alongside cannabis operations.
Reading The Reporting Perimeter
The businesses included in a company's financial statements can change after acquisitions, divestitures or changes in control. A consolidated income statement generally includes the results of controlled subsidiaries, whereas an interest that is not consolidated can appear through a different accounting treatment. As a result, a percentage change in total revenue may combine changes in existing operations with changes in which businesses are included. Notes describing the reporting entity and significant transactions provide the context needed for a meaningful comparison.
Goodwill and other intangible assets deserve separate attention in a company that has acquired businesses or brands. Goodwill reflects, among other things, value paid beyond identifiable net assets in an acquisition. Accounting rules require companies to assess whether certain assets have lost carrying value. An impairment charge can reduce reported earnings without representing a cash payment in that period, but it also records a reduction in the accounting value of assets already on the balance sheet.
Cash flow classification adds another layer to the picture. Operating cash flow records cash associated with running the business, while investing cash flow includes transactions involving long-lived assets and businesses. Financing cash flow includes transactions with lenders and shareholders. Proceeds from selling an operation can increase cash without being recurring cash generated by the remaining business. Reading these categories together with transaction notes helps explain why cash balances can move differently from reported earnings.
Conclusion: Is CGC Stock Worth Analyzing in 2027?
Canopy Growth has a business model with clear drivers that can be tracked through its reported results, and a set of risks that are specific to its industry and financial position.
A balanced assessment considers growth, profitability, balance-sheet strength, valuation and risk together. CGC is a company worth monitoring for what its results reveal about its business.